- CARO 2020 applies to every company, including a foreign company, except five categories listed in paragraph 1(2).
- A private company can escape CARO by two separate routes: being a small company, or meeting all the conditions of the private-company exemption in paragraph 1(2)(v).
- For the private-company route, ICAI counts borrowings from banks and NBFCs, on any day of the year, in aggregate; and "revenue" means total income, including other income.
- Applicability is judged on the company's status at the balance sheet date.
- CARO does not apply to the report on consolidated financial statements, except clause 3(xxi).
The Companies (Auditor's Report) Order, 2020 — CARO 2020 — was issued by the Central Government under section 143(11) of the Companies Act, 2013 by notification S.O. 849(E) dated 25 February 2020. Paragraph 1(2) says it applies to every company, including a foreign company as defined in section 2(42), and then lists five exceptions. Everything turns on those five exceptions, and on reading the fifth one exactly.
The five exemptions in paragraph 1(2)
| # | CARO 2020 does not apply to |
|---|---|
| (i) | A banking company as defined in section 5(c) of the Banking Regulation Act, 1949 |
| (ii) | An insurance company as defined under the Insurance Act, 1938 |
| (iii) | A company licensed to operate under section 8 of the Companies Act |
| (iv) | A One Person Company (section 2(62)) and a small company (section 2(85)) |
| (v) | A private limited company, not being a subsidiary or holding company of a public company, having paid-up capital and reserves and surplus of not more than ₹1 crore as on the balance sheet date, which does not have total borrowings exceeding ₹1 crore from any bank or financial institution at any point of time during the financial year, and which does not have total revenue as disclosed in Schedule III (including revenue from discontinuing operations) exceeding ₹10 crore during the financial year as per the financial statements |
Paragraph 2 adds that the Order does not apply to the auditor's report on consolidated financial statements, except clause (xxi) of paragraph 3.
Two separate routes for a private company
This is where most mistakes happen. A private company can be outside CARO by being a small company (exemption iv) or by meeting the private-company conditions (exemption v). They are separate tests with very different limits:
| Test | Route A — small company | Route B — private-company exemption |
|---|---|---|
| Type | Not a public company (and not section 8 or governed by a special Act) | A private company |
| Group position | Not a holding or subsidiary company of any company or body corporate | Not a subsidiary or holding company of a public company |
| Capital | Paid-up share capital ≤ ₹10 crore | Paid-up capital plus reserves and surplus ≤ ₹1 crore, as on the balance sheet date |
| Size of business | Turnover of the immediately preceding year ≤ ₹100 crore | Total revenue of this year ≤ ₹10 crore |
| Borrowings | No test | Bank / financial institution borrowings never above ₹1 crore at any point in the year |
| How many must be met | All | All — ICAI: "even if one of the conditions is not satisfied, the Order would be applicable" |
ICAI's Guidance Note (paragraph 12) also makes clear that a company that is a small company remains exempt "even if it falls under any of the criteria specified for private company". In other words, check Route A first; only if it fails do you need Route B.
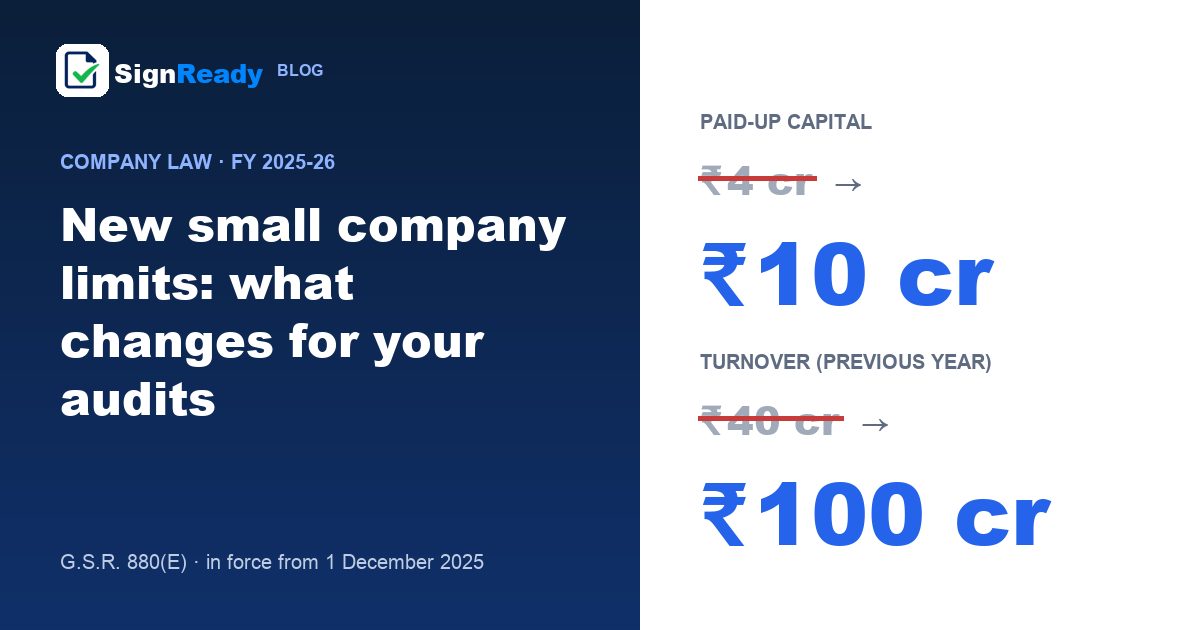
The small company limits were raised to ₹10 crore and ₹100 crore from 1 December 2025 — see our guide on the new small company limits for the exclusions and the measurement dates.
How ICAI reads the private-company conditions
Paid-up capital and reserves and surplus
- For financial statements under Schedule III Division I (Accounting Standards), both capital and revenue reserves count, including any revaluation reserve (Guidance Note, paragraph 19).
- For Ind AS financial statements under Division II, use the Division II components of reserves and surplus — ICAI notes that revaluation surplus is not part of them (paragraph 20).
- A debit balance in the statement of profit and loss is netted in computing reserves and surplus.
- Calls unpaid are deducted and the amount originally paid up on forfeited shares is added; share application money is not part of paid-up capital (paragraph 18).
Borrowings from banks or financial institutions
- The limit is on the aggregate of all banks and financial institutions, not per lender, and on the amount outstanding on any day — not the sanctioned limit. A fluctuating cash credit account that crosses ₹1 crore on even one day, together with other borrowings, brings the company into CARO (paragraph 22).
- Term loans, demand loans, cash credit, overdraft (including an overdraft against the company's own fixed deposits), bills discounted, current maturities of long-term loans and credit card dues all count. Non-fund facilities count once they devolve — for example, an invoked and encashed bank guarantee or a devolved letter of credit. For term loans, interest accrued and due is included; interest accrued but not due is not.
- "Financial institution" includes an NBFC (paragraph 23), so vehicle loans and other loans from NBFCs count too. Loans from directors, relatives or other companies that are not banks or financial institutions do not count for this test.
Total revenue
- Revenue means total income as disclosed in Schedule III — revenue from operations plus other income — including revenue from discontinuing operations (paragraph 24).
Based on the TB and the answers you enter, SignReady works through small-company status and the private-company conditions, shows which test decided it, and records the reason for your review.
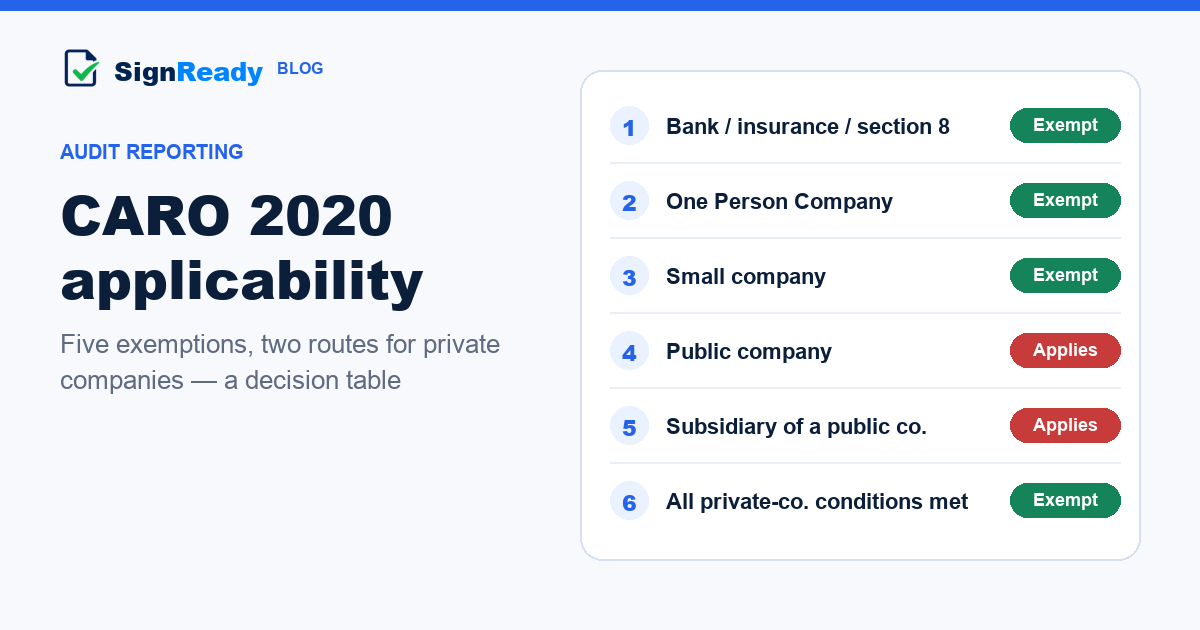
Decision table: does CARO 2020 apply?
Work through the steps in order and stop at the first answer.
| Step | Question | If yes |
|---|---|---|
| 1 | Is it a banking company, an insurance company or a section 8 company? | CARO does not apply |
| 2 | Is it a One Person Company? | CARO does not apply |
| 3 | Is it a small company — not a public company, not a holding or subsidiary company, not section 8 or governed by a special Act, with paid-up capital ≤ ₹10 crore and previous-year turnover ≤ ₹100 crore? | CARO does not apply |
| 4 | Is it a public company — including a private company that is a subsidiary of a public company, which section 2(71) deems to be public? | CARO applies |
| 5 | Is the private company a holding or subsidiary company of a public company? | CARO applies |
| 6 | Are capital plus reserves ≤ ₹1 crore at the balance sheet date, and bank / FI borrowings never above ₹1 crore during the year, and total revenue ≤ ₹10 crore? | Yes: CARO does not apply. No: CARO applies. |
Worked examples for FY 2025-26
| Company | Facts | Result |
|---|---|---|
| P | Private, standalone. Paid-up capital ₹50 lakh, reserves ₹80 lakh (total ₹1.3 crore). FY 2024-25 turnover ₹5.5 crore; FY 2025-26 total revenue ₹6 crore. No borrowings. | Exempt through Route A — it is a small company, so the ₹1 crore capital-and-reserves test in Route B does not matter. |
| Q | Private, subsidiary of an Indian private company. Capital plus reserves ₹60 lakh; total revenue ₹4 crore; cash credit peaked at ₹1.4 crore in November. | CARO applies. Route A fails (it is a subsidiary). Route B fails on borrowings — the peak, not the year-end balance, is tested. |
| R | Registered as a private company, 60% held by an unlisted public company. Capital plus reserves ₹40 lakh; revenue ₹2 crore; no borrowings. | CARO applies. Under the proviso to section 2(71) it is deemed to be a public company. Route A fails (subsidiary); Route B fails at the first condition — it is a subsidiary of a public company. |
| S | One Person Company with total revenue of ₹30 crore. | Exempt — OPCs are excluded by paragraph 1(2)(iv) whatever their size. |
Documenting the conclusion
Whichever way the answer goes, record it in the working papers: the route used, the figures for each test (with the balance sheet date and the source — TB, bank statements for the peak borrowing, the audited P&L for last year's turnover) and who reviewed it. Borrowing peaks deserve a specific note, because the year-end balance sheet does not show them; ask the client for month-wise or day-wise bank balances where a cash credit or overdraft account comes close to the limit.
Frequently asked questions
Does CARO 2020 apply to a private company whose cash credit limit is ₹2 crore but whose balance never exceeded ₹90 lakh?
The test is the amount outstanding, not the sanctioned limit. ICAI's Guidance Note looks at the amount outstanding on any day during the year, together with other bank and financial-institution borrowings. If the aggregate never exceeded ₹1 crore, the borrowing condition is met — the other conditions must still be checked.
Is the ₹10 crore revenue test on revenue from operations only?
No. ICAI reads "total revenue" as total income disclosed under Schedule III — revenue from operations plus other income — including revenue from discontinuing operations.
Do NBFC loans count in the ₹1 crore borrowing test?
Yes. ICAI's Guidance Note says the term "financial institution" also covers a non-banking financial company, so NBFC loans are counted along with bank borrowings.
Can a subsidiary of a foreign company use the private-company exemption?
It cannot be a small company, because it is a subsidiary company. Whether it can use the private-company route depends on whether its holding company is a "public company". The Act defines a public company in section 2(71) by reference to a company registered under the Act, so a foreign body corporate is generally not regarded as one — but record your reasoning, as this is a matter of interpretation.
Does CARO apply to the audit report on consolidated financial statements?
Only clause (xxi) of paragraph 3 — qualifications or adverse remarks in the CARO reports of the companies included in the consolidated financial statements. The rest of the Order does not apply to the consolidated report.
Sources
- Companies (Auditor's Report) Order, 2020 — S.O. 849(E) dated 25 February 2020 (full text in Appendix I of ICAI's Guidance Note, Revised 2022, hosted by CAG)
- ICAI, Guidance Note on the Companies (Auditor's Report) Order, 2020 (Revised 2022 edition), paragraphs 11–24
- Companies Act, 2013 — sections 2(62), 2(71), 2(85), 143(11) (India Code)
- G.S.R. 880(E) dated 1 December 2025 — revised small company limits (Gazette of India)
SignReady assists the CARO, small company, cash flow and IFC assessment for each finalisation, for auditor review, and lays out the CARO 2020 clauses with what the books show — first 3 finalisations free.
Version history: 1 Oct 2026 — first published.