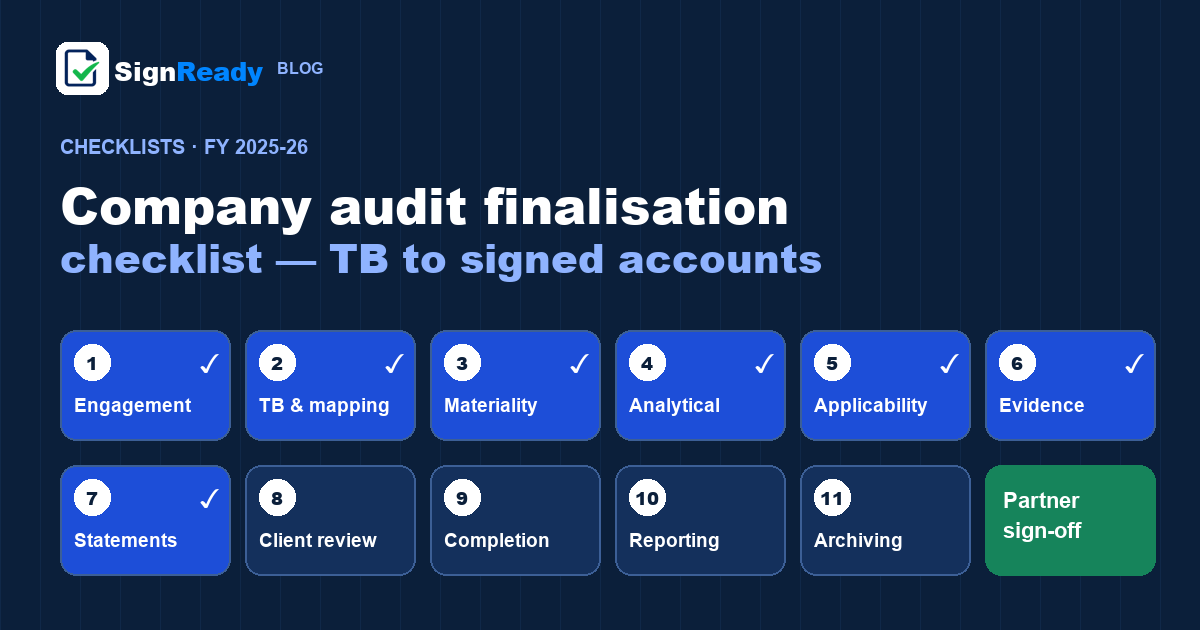
- A company audit finalisation runs through eleven stages — from acceptance to archiving — and each stage has a standard or provision behind it.
- Settle applicability early: small company, CARO 2020, cash flow statement, IFC reporting and the Accounting Standards (SMC) test all change the work and the report.
- Use analytical procedures at planning and, where they suit the risk, as substantive procedures — and always near the end of the audit to support the overall conclusion (SA 520, paragraph 6).
- Date the written representations as near as practicable to, but not after, the date of the auditor's report (SA 580); date the report no earlier than the evidence supports (SA 700).
- A tax audit, where needed, is a separate report under section 44AB of the Income-tax Act, 1961 for FY 2025-26 — it does not follow from the company-audit workflow.
Every firm has a finalisation checklist; the difference is whether it is followed the same way on every file. This one is written for company audits of FY 2025-26 under the Companies Act, 2013 and the Standards on Auditing, stage by stage, with the provision or standard behind each step. Use it as a base and add your firm's own points.
1. Engagement and acceptance
- Appointment under section 139 and eligibility under section 141 confirmed; the company files ADT-1 for the appointment.
- Independence and ethical requirements confirmed for the engagement team.
- Engagement letter agreed and signed (SA 210), setting out management's responsibility for the financial statements.
- First year only: communication in writing with the previous auditor before accepting — clause (8) of Part I of the First Schedule to the Chartered Accountants Act, 1949 — with proof of delivery on file.
- First year, or a modified report last year: plan the work on opening balances and read last year's audit report (SA 510).
2. Trial balance and mapping
- Final trial balances for the current and previous year obtained and agreed to the books.
- Ledgers mapped to the heads of the applicable Schedule III division — Division I (Accounting Standards), Division II (Ind AS) or Division III (Ind AS NBFCs) — consistently across both years; regroupings noted.
- Every revised TB from the client compared with the previous version, and the changes explained.
3. Materiality and risk
- Overall materiality and performance materiality determined and documented (SA 320).
- Risks of material misstatement identified and assessed, including fraud risks such as revenue recognition and management override (SA 315, SA 240).
4. Analytical review
- CY vs PY review with expectations, a threshold, ratios and investigated differences — see our SA 520 checklist.
- Points that need the client turned into written queries, with a record of each reply and the evidence received.
5. Applicability
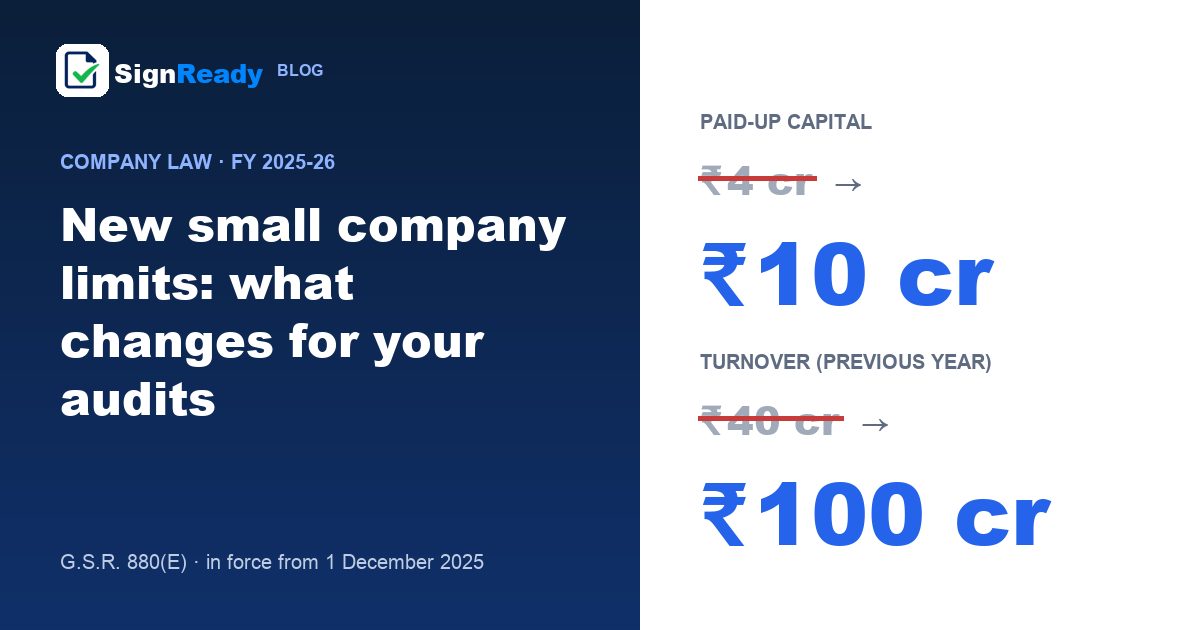
- Small company status under section 2(85): not a public, holding, subsidiary, section 8 or special-Act company; paid-up capital up to ₹10 crore and previous-year turnover up to ₹100 crore (limits in force from 1 December 2025) — see the new small company limits.
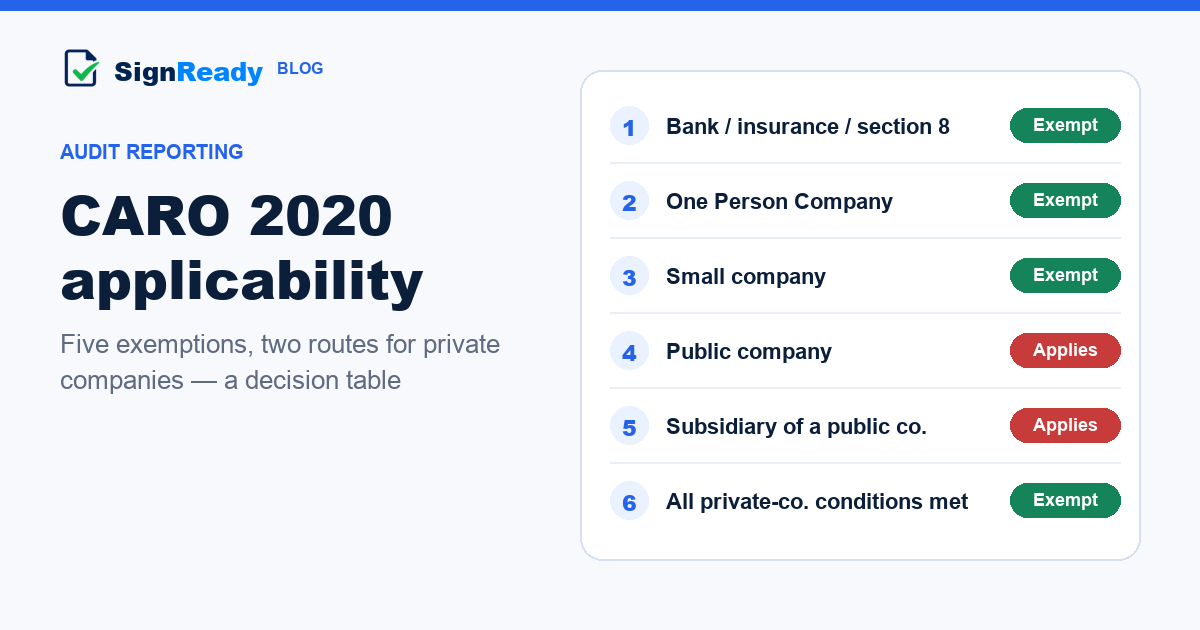
- CARO 2020 — not applicable to banking, insurance and section 8 companies, OPCs and small companies, or to a private company that meets all the private-company conditions; for consolidated financial statements only clause 3(xxi) applies — see CARO 2020 applicability.
- Cash flow statement (proviso to section 2(40)) and reporting on internal financial controls with reference to financial statements (section 143(3)(i), read with the 2017 exemption notification for private companies and its ROC-filing condition).
- Accounting framework: Accounting Standards (and the SMC relaxations) or Ind AS.
SignReady takes each finalisation through set-up, review and queries, documentation, statements, client review and partner sign-off — with progress by stage and a central record of work and client queries.
6. Evidence on the key areas
- External confirmations for bank balances, borrowings, receivables and payables where planned (SA 505).
- Attendance at inventory counting where inventory is material (SA 501).
- Related parties identified and transactions tested (SA 550).
- Accounting estimates — provisions, useful lives, impairment — evaluated (SA 540).
- Laws and regulations, and pending litigation and claims — the latter also feed Rule 11(a) (SA 250, SA 501).
- Going concern assessed (SA 570).
7. Draft financial statements
- Balance Sheet, Statement of Profit and Loss, cash flow statement unless exempt, statement of changes in equity where applicable, and notes — in the applicable Schedule III format, with comparative figures.
- Disclosures prescribed by the applicable Schedule III division checked — including, under Division I or II, the Additional Regulatory Information with the eleven ratios and explanations for changes above 25% (Division III prescribes its own NBFC ratios), and the amounts due to micro and small enterprises.
- Accounting Standards disclosures checked against the framework that applies.
8. Client review and approval
- Draft statements sent to the client; all queries closed or carried as open points for the partner.
- Financial statements approved by the Board and signed as required by section 134.
- The version approved is the version you audited — check for edits made outside your working file.
9. Completion
- Subsequent events reviewed up to the date of the report (SA 560).
- Written representations obtained, dated as near as practicable to, but not after, the date of the auditor's report (SA 580).
- Board's report and other information read for material inconsistencies (SA 720).
- Analytical procedures near the end of the audit to support the overall conclusion (SA 520, paragraph 6).
- Misstatements evaluated (SA 450); engagement quality review where your firm's policy requires it.
10. Reporting and sign-off
- Opinion and report wording (SA 700; SA 705 and SA 706 where there is a modification or an emphasis of matter; SA 701 key audit matters for listed companies).
- CARO 2020 annexure where it applies (for consolidated financial statements, only clause 3(xxi)); internal financial controls annexure where it applies.
- Rule 11 of the Companies (Audit and Auditors) Rules, 2014: (a) pending litigations, (b) material foreseeable losses, (c) transfers to the Investor Education and Protection Fund, (e) the representations on funds routed through intermediaries, (f) dividend compliance with section 123, and (g) the audit trail (edit log) in the accounting software. Clause (d) has been omitted.
- Remuneration to directors — section 197(16), for public companies.
- Report dated no earlier than the date on which sufficient appropriate evidence was obtained, including evidence that the financial statements have been prepared and that those with the authority have taken responsibility for them (SA 700).
- UDIN generated for the report as required by ICAI.
11. Archiving
- The final audit file assembled after the report date — SA 230's application material says this is ordinarily done within 60 days after the date of the auditor's report.
- No deletion of documentation after assembly; any later additions recorded with who made them, when and why (SA 230).
- Audit documentation retained for at least seven years from the date of the auditor's report (or, where later, the date of the group auditor's report), or longer where law, regulation or your firm's policy requires.
Where the tax audit fits
If the company also needs a tax audit for FY 2025-26, that is a separate report under section 44AB of the Income-tax Act, 1961 — for a company, whose accounts are audited under the Companies Act, the report is in Form 3CA with the particulars in Form 3CD. Its applicability, forms and due date follow the income-tax law and the CBDT's notifications for the year, not the company-audit stages above. Plan it alongside the company audit, but test it separately.
One-page summary
| Stage | Output | Main reference |
|---|---|---|
| Engagement | Engagement letter; previous-auditor letter (first year) | SA 210; CA Act, First Schedule, Part I, clause (8) |
| TB and mapping | Mapped TBs, both years; revised-TB log | Schedule III |
| Materiality and risk | Materiality working; risk assessment | SA 320; SA 315; SA 240 |
| Analytical review | CY vs PY with ratios; query list; near-end review | SA 520 |
| Applicability | Small company, CARO, cash flow, IFC, SMC conclusions | Sections 2(85), 2(40), 143(3)(i); CARO 2020 |
| Evidence | Confirmations, stock, related parties, estimates, going concern | SA 505, 501, 550, 540, 570 |
| Statements | Draft Schedule III statements and notes | Schedule III; Accounting Standards |
| Client review | Approved statements, closed queries | Section 134 |
| Completion | Subsequent events, representation letter, final review | SA 560, 580, 720, 520, 450 |
| Reporting | Auditor's report, CARO and IFC annexures, Rule 11, UDIN | SA 700–706; CARO 2020; Rule 11 |
| Archiving | Assembled audit file | SA 230 |
Frequently asked questions
How is finalisation different from the audit itself?
Finalisation is the work that turns the books into approved financial statements — closing entries, mapping, schedules and disclosures. The audit is the independent examination that leads to the auditor's report. In small companies both often happen together, which is why a single checklist that separates preparation from audit evidence is useful.
When should the management representation letter be dated?
SA 580 requires the written representations to be dated as near as practicable to, but not after, the date of the auditor's report.
Can the auditor sign before the Board approves the financial statements?
SA 700 requires the report to be dated no earlier than the date on which the auditor has obtained sufficient appropriate evidence, including evidence that all the statements have been prepared and that those with the recognised authority have taken responsibility for them. In a company that is the Board's approval of the financial statements.
Is communication with the previous auditor needed for every audit?
It is needed before accepting a position as auditor previously held by another chartered accountant — clause (8) of Part I of the First Schedule to the Chartered Accountants Act, 1949. Keep proof that the letter was delivered.
Sources
- Companies Act, 2013 — sections 2(40), 2(85), 123, 134, 139, 141, 143, 197(16) and Schedule III (India Code)
- G.S.R. 880(E) dated 1 December 2025 — revised small company limits (Gazette of India)
- Companies (Auditor's Report) Order, 2020 — S.O. 849(E) dated 25 February 2020 (full text in Appendix I of ICAI's Guidance Note, Revised 2022, hosted by CAG)
- Companies (Audit and Auditors) Rules, 2014 — rule 11 (as amended)
- ICAI — Standards on Auditing: SA 210, 230, 240, 250, 315, 320, 450, 501, 505, 510, 520, 540, 550, 560, 570, 580, 700, 701, 705, 706, 720
- Chartered Accountants Act, 1949 — First Schedule, Part I, clause (8)
- Income-tax Act, 1961 — section 44AB; Forms 3CA and 3CD
Staff prepare, SignReady flags, the partner reviews and signs — alongside Tally and Excel. Your first 3 finalisations are free.
Version history: 2 Oct 2026 — first published.